The BC home flipping tax and a new multiplex: when a quick sale is exempt
B.C. taxes profit on residential property sold within 730 days of buying it, at up to 20 percent. Demolishing a house and building new homes is one of the listed exemptions, but you still have to file a return within 90 days of the sale.
In short, The BC home flipping tax took effect on January 1, 2025. It applies to profit from selling B.C. residential property, including presale contracts, owned for less than 730 days, at 20 percent of net taxable income for a sale within 365 days and a rate that decreases over the following 365 days. Individuals, corporations, partnerships and trusts are all covered. The province lists exemptions for demolishing a housing unit and building a new one, for adding a housing unit to a property with an existing home, for building on land with no housing unit, and for builders and developers acting in the ordinary course of business. A seller who relies on one of these exemptions must still file a return within 90 days of the sale.
Since January 1, 2025, B.C. has taxed the profit on residential property sold within two years of buying it. For people who trade houses, that was the point. For landowners and partners building a multiplex, the tax comes up in a different way: the timeline from purchase to the sale of finished units can fall inside the window, and the exemptions only help if the seller knows to claim them.
This post covers how the tax works, which of its exemptions apply to building new homes, and the filing step owners most often miss.
What the tax covers
The BC home flipping tax applies to the profit a person earns from selling a property in B.C., including presale contracts, when they owned it for less than 730 days. The province defines a person broadly: an individual, a corporation, a partnership or a trust.
The rate is 20 percent of net taxable income on a property sold within 365 days of acquiring it. Over the next 365 days the rate decreases gradually. After 730 days, the tax no longer applies.
For a multiplex seller, the question is timing: when the property was acquired, and when each sale closes. The build schedule decides which side of the window a sale lands on. Our single-family lot to fourplex timeline lays out each stage between purchase and sale, and every stage adds months.
There is a deduction of up to $20,000 of taxable income for a seller who owned the property for at least 365 consecutive days and lived in it as their principal residence. The province also publishes a set of life circumstance exemptions, such as separation or a death in the family, on a separate page.
A landowner who has held a Vancouver lot for ten years is outside the tax on that land. A buyer who picked up a teardown last spring is inside the window, and needs to know which exemption applies.
The exemptions that apply to building homes
The province lists a group of exemptions for builders, developers, and building or renovating activity. Four of them matter for a multiplex.
- Demolition and rebuild: if a housing unit is demolished and a new housing unit is built or placed on the property, the property is exempt.
- Additional units: if a housing unit is added to an existing home (a basement suite, for example) or built on a property that already has a home, the property is exempt.
- Vacant residential land: if you build on residential property that had no housing unit when you acquired it, you are exempt for the building of that unit.
- Builders and developers: a person who, in the ordinary course of business, buys property to build on it, or builds on property held for that purpose, is exempt.
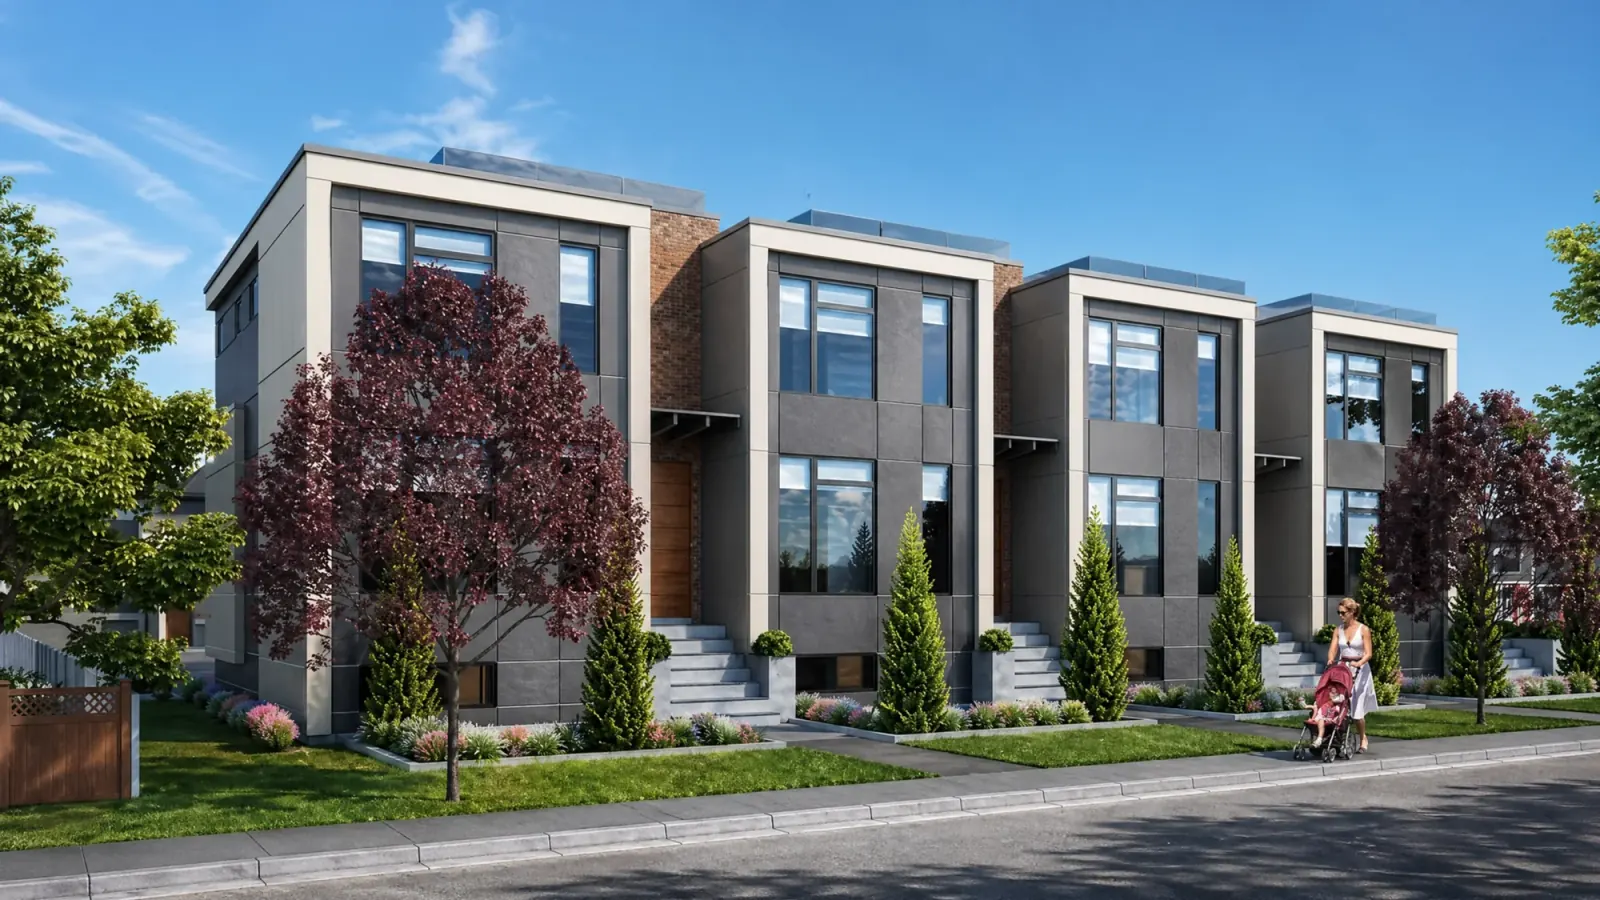
Most multiplex projects in Vancouver, Burnaby and Richmond fit the first case. An older house comes down and three to six new homes go up in its place under the province's small-scale multi-unit housing rules. A project that keeps the house and adds a laneway home or a garden suite fits the second.
There is also an exemption for a substantial renovation of a housing unit. That is less common on a multiplex site. It covers owners who keep and renovate the existing house.
You still have to file
This is the step we see missed. For the building and development exemptions, the province says it plainly: you will still need to file a BC home flipping tax return, but you will not have to pay the tax if you meet the requirements.
The return is due within 90 days of the sale. It is required whenever you sold a taxable property within 729 days of acquiring it, or whenever the exemption you are relying on requires a return to claim it.
On a multiplex that sells four strata units over several months, that can mean several sales and several 90-day deadlines. Put them on the same calendar as the closing dates, and tell your accountant when each unit completes.
Keep the records that prove the exemption
An exemption is something you claim, so the evidence matters. For a demolition and rebuild, the demolition permit, the building permit and the occupancy permit, with the dates on each, show the building activity the exemption describes. For an added unit, the permit that created it does the same job.
Keep those documents with the purchase records for the land, and give copies to whoever files the return. Gathering them after a sale, with a 90-day deadline running, is harder than filing them as each permit is issued.
Three situations to compare
The long-held family lot. Take a couple in Dunbar who have owned their house since 2009 and partner with a developer to build a fourplex. The land has been theirs for far longer than 730 days, so the tax does not reach the land they already held, and the province does not require a return for property owned longer than 729 days. How the holding period is counted for new strata lots created when the lot is subdivided is a technical question the province's overview pages do not answer directly. Confirm it with your accountant before the first unit sells.
The recent teardown purchase. Take an investor who bought a Burnaby house in 2025 to replace with a multiplex. If a sale happens inside 730 days of that purchase, the tax applies unless an exemption does. Demolishing the house and building new units is one of the listed exemptions, and the return still has to be filed.
The partnership. In a GP/LP partnership, the partnership is a person for the purposes of this tax. The structure does not take the project outside the rules. Agree before the first closing who tracks the dates and files each return, and write it into the partnership reporting.
Presale buyers are covered too
The tax includes the sale of presale contracts. If units in a multiplex are sold before completion, a buyer who assigns their contract to someone else within the holding period is inside the tax, unless an exemption applies to them.
The buyer is the one who owes it. It still changes how some buyers think about a presale, and it is worth being clear about when a project is marketed before it is finished.
What it does not replace
The flipping tax sits alongside other taxes on a new multiplex. It is separate from GST on the sale of new homes and from property transfer tax on the purchase, which we cover in the tax rules on new multiplex homes. Federal income tax on the profit is a separate question again.
A single sale can involve more than one of them, and each has its own forms and deadlines.
What to do before the first sale
- Write down the date the land was acquired, by whom, and in what name.
- Identify which exemption applies to the project, if any, and keep the permits and records that show the building activity.
- Work out the 730-day date for each property and each seller.
- Agree who files the return for each sale and how the 90-day deadline is tracked.
- Ask your accountant how the holding period is counted for new strata lots on your lot.
Frequently asked
Does the BC flipping tax apply when I sell units in a new multiplex?
It can, if the property is sold within 730 days of when it was acquired. The province exempts several kinds of building activity, including demolishing a housing unit and building a new one, and adding housing units to a property with an existing home. A seller who relies on an exemption still has to file a return within 90 days of the sale.
What is the BC home flipping tax rate?
The tax is 20 percent of net taxable income on a property sold within 365 days of acquiring it, and the rate decreases over the next 365 days. After 730 days of ownership, the tax does not apply. It took effect on January 1, 2025.
I have owned my Vancouver lot for ten years. Does the flipping tax affect my multiplex?
Not on the sale of land you have held that long, because the tax only covers property disposed of within 730 days of acquiring it, and no return is required when you owned it longer than 729 days. How the dates are counted for new strata lots created from your lot is a question to confirm with your accountant.
Does the flipping tax apply to a development partnership?
The tax applies to a person, and the province's definition of a person includes an individual, a corporation, a partnership or a trust. A GP/LP partnership that buys and sells residential property is inside its scope, and would rely on the same exemptions as any other seller.
Do I still have to file if my sale is exempt?
For the building and development exemptions, yes. The province states that you will still need to file a BC home flipping tax return but will not have to pay the tax if you meet the requirements. The return is due within 90 days of the sale.
Does the flipping tax cover presale contracts for multiplex units?
Yes. The province's description of the tax includes selling presale contracts. A buyer who assigns a presale contract for a multiplex unit within the holding period is inside the tax, which is a point worth raising with buyers when a project is marketed before completion.
What records prove a multiplex sale qualifies for the demolition and rebuild exemption?
The demolition permit, the building permit, and the occupancy permit, each showing the dates the work happened. Those three documents demonstrate the building activity the exemption describes. Keep them with the purchase records for the land from the start, not gathered after a sale while a 90-day filing deadline is already running.
Does the flipping tax apply separately to each strata unit sold from one multiplex?
Each sale is its own disposition for tax purposes, so a multiplex that sells four strata units over several months can involve four separate 730-day calculations and four separate 90-day filing deadlines. Put every closing date on the same calendar as the permits, and tell your accountant when each unit completes.
Timing is part of every decision about whether to sell, develop or hold a Vancouver lot, and this tax is one more date on that calendar. If you are weighing a multiplex on a lot you own and want the timeline laid out before you commit, book a free consultation.
Written by
Acquisitions and Development
Trent Praski leads investment and development at Venture Pacific, sourcing missing-middle opportunities across Metro Vancouver and the Fraser Valley and structuring transparent homeowner and investor partnerships.
Full profile